Form 5472 Line-by-Line Guide for Foreign-Owned US LLCs
Learn how to fill out Form 5472 and pro forma Form 1120 for your foreign-owned single-member US LLC. Line-by-line guide, worked example, fax and mailing rules.
If you are a non-US resident who owns a single-member US limited liability company (LLC), learning how to fill out Form 5472 and its companion return is an essential yearly chore. For US tax purposes, your LLC is classified as a foreign-owned domestic disregarded entity (foreign-owned U.S. DE), meaning the company does not pay corporate income tax by default, but it must report its ownership and cross-border transactions to the Internal Revenue Service (IRS).
To file correctly, you do not submit Form 5472 alone. You must attach it to a "pro forma" Form 1120 (U.S. Corporation Income Tax Return), writing "Foreign-owned U.S. DE" across the top, and deliver both documents together by fax or dedicated mail. Missing this requirement or submitting an incomplete form exposes the LLC to a $25,000 penalty for each failure.
In short:
- Foreign owners of single-member US LLCs must file Form 5472 with a pro forma Form 1120 for every year the LLC had a reportable transaction with them (money put in or taken out counts), even if the LLC had no revenue.
- The pro forma Form 1120 acts as a cover page: you only complete the LLC's name and address and items B (the EIN) and E on the first page.
- Reportable transactions on Form 5472 include contributions of capital, distributions, owner loans, reimbursements, and any operational fees between you and the company.
- The packet cannot be submitted through standard commercial e-file platforms; you must fax it to 855-887-7737 or mail it to the IRS PIN Unit in Ogden, Utah.
- The standard due date matches the federal corporate tax deadline (usually April 15), with a 6-month extension available via Form 7004.
Who needs this
Under Internal Revenue Code (IRC) Section 6038A, any domestic disregarded entity that is 100% owned (directly or indirectly) by a foreign person must file Form 5472 when it engages in reportable transactions.
You must file if:
- You are an individual who is not a US citizen or resident alien, or you are a foreign legal entity.
- You own 100% of a US LLC formed under state law (such as Delaware, Wyoming, or New Mexico).
- The LLC has not made an election on Form 8832 to be taxed as a corporation (it remains a disregarded entity).
- The company engaged in at least one reportable transaction during the calendar year (including formation expenses paid from personal funds, capital injections, withdrawals, or sales of goods and services with you or your foreign entities).
You do NOT need this specific filing if:
- Your LLC has two or more owners and is treated as a partnership (partnerships file Form 1065 instead).
- The LLC is 100% owned by a US citizen or permanent resident (green card holder).
- You elected to treat your LLC as a standard C corporation on Form 8832 (in which case you file a standard, full Form 1120 and attach Form 5472 under normal corporate rules).
What you need before you start
Gather the following items before drafting your forms:
- LLC Legal Documents: Your Articles of Organization and Certificate of Formation to confirm the legal name, state of registration, and formation date.
- LLC EIN Confirmation Letter (Form CP 575 or 147C): The official 9-digit US tax identification number issued to your LLC. No EIN yet? Without an SSN or ITIN you cannot use the online application; you apply with Form SS-4 (PDF) by fax or mail, and the SS-4 instructions say "only international applicants can receive an EIN by telephone." The fax numbers depend on where the business is located; take them from the current instructions.
- Foreign Tax Identification Number (FTIN): the tax identification number issued to you by your country of tax residence (for example the French "numéro fiscal").
- Accounting Ledger and Bank Statements: A record of every transaction between you (the owner) and the LLC during the tax year. This includes initial startup contributions, cash deposits, personal funds used to pay state fees or registered agent charges, and owner distributions.
- Principal Business Activity Code: A 6-digit NAICS code representing the LLC's core commercial operations (the list is in the Instructions for Form 1120).
How to fill out Form 5472 and the pro forma Form 1120
A foreign-owned US disregarded entity cannot file Form 5472 as a standalone document. The IRS Instructions for Form 5472 specify that it must be filed as an attachment to a "pro forma" Form 1120. A pro forma return is a shell return used exclusively to carry information; you do not fill in income, deductions, or tax schedules on this Form 1120.
Download the official forms before you start:
Step 1: The Pro Forma Form 1120
Use the version of Form 1120 (PDF) matching the reporting year. At the very top of the page, above the form title, write or type in bold text: Foreign-owned U.S. DE.
Per the official instructions, you only complete the following identity items on the first page:
| Item / Box | What the form asks | What to enter | Example |
|---|---|---|---|
| Top Banner | Tax Year Beginning / Ending | Calendar year dates (unless a fiscal year applies). | 01/01/2025 to 12/31/2025 |
| Name | Legal name of entity | The exact legal name of your LLC as registered. | Meridian Cloud Solutions LLC |
| Address | Street, suite, city, state, ZIP | Your official LLC business address or US registered agent address. | 1209 Orange St, Wilmington, DE 19801 |
| Item B | Employer identification number | The 9-digit EIN assigned to the LLC. | 12-3456789 |
| Item E | Checkboxes: (1) Initial return, (2) Final return, (3) Name change, (4) Address change | Check box (1) if this is the first year filing, box (2) if dissolved, or leave blank if an ongoing filer. | Check box (1) for first year |
| Lines 1–37 | Income, Deductions, Tax, Payments | LEAVE COMPLETELY BLANK. Do not write zeros. | Blank |
| Sign Here | Signature, Date, Title | Your signature, date of signing, and title as owner. | Signature, Date, Sole Member |
Leave Pages 2 through 6 of Form 1120 completely blank (including Schedule C, Schedule J, Schedule K, Schedule L, Schedule M-1, and Schedule M-2).
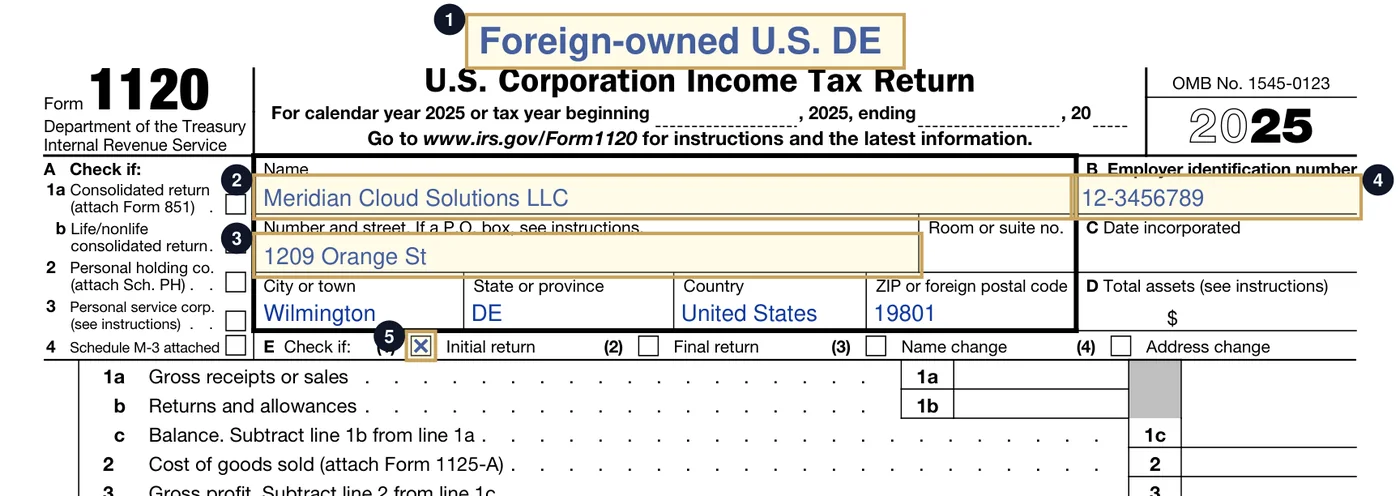
- 1"Foreign-owned U.S. DE" written across the top
- 2Name of the LLC
- 3Address (street, then city, state, country and ZIP on the next line)
- 4Item B: the LLC's EIN
- 5Item E(1): Initial return, checked for the first year
Everything else stays blank, including item D and the income lines below.
Official IRS form, filled in with this guide's fictional example. Click to enlarge.Step 2: Form 5472 Walkthrough
Complete Form 5472 (PDF) (Rev. December 2023). The form asks you to "enter all information in English and money items in U.S. dollars."
Part I: Reporting Corporation
All reporting entities must complete Part I. For our purposes, the "reporting corporation" is your single-member LLC.
| Line | What the form asks | What to enter | Example |
|---|---|---|---|
| Top | Tax year beginning and ending | The dates matching your pro forma 1120. | 01/01/2025 to 12/31/2025 |
| 1a | Name and address of reporting corporation | The LLC's legal name and official mailing address. | Meridian Cloud Solutions LLC, Wilmington, DE |
| 1b | Employer identification number | The LLC's 9-digit EIN. | 12-3456789 |
| 1c | Total assets | The LLC's total assets at year end. The instructions point to Form 1120, item D; since the pro forma 1120 leaves item D blank, use the LLC's year-end balance sheet. | $35,000 |
| 1d | Principal business activity | Your core commercial activity. | Computer systems design services |
| 1e | Principal business activity code | The 6-digit NAICS code for your activity. | 541512 |
| 1f | Total value of gross payments made or received reported on this Form 5472 | Lines 22 and 36 of Part IV, plus the value of Part VI transactions and, for a foreign-owned U.S. DE, the Part V transactions (contributions, distributions, formation costs). | $22,000 |
| 1g | Total number of Forms 5472 filed for the tax year | A separate Form 5472 is filed for each related party (person or company) the LLC had reportable transactions with. Enter the total, including this one. | 1 |
| 1h | Total value of gross payments reported on all Forms 5472 | Matches line 1f if only one Form 5472 is filed. | $22,000 |
| 1j | Initial year checkbox | Check this box if this is the first Form 5472 filed for the entity. | Checked (if Year 1) |
| 1k | Total number of Parts VIII attached | Part VIII is only for cost sharing arrangements. Enter 0 if none. | 0 |
| 1l | Country of incorporation | Enter United States. |
United States |
| 1m | Date of incorporation | The exact filing date on your Certificate of Formation. | 03/15/2025 |
| 1n | Country(ies) under whose laws the reporting corporation files an income tax return as a resident | A disregarded LLC does not file an income tax return in its own name. Practice varies on what to enter here; confirm with your preparer. | Confirm with your preparer |
| 1o | Principal country(ies) where business is conducted | The country or countries where the LLC's business is actually carried out (often where you work from). The instructions say: do not enter "worldwide". | France |
| Line 2 | Foreign person 50% ownership checkbox | Check this box (you own 100%). | Checked |
| Line 3 | Foreign-owned U.S. DE checkbox | Check this box. It tells the IRS the LLC is a foreign-owned disregarded entity treated as a corporation for section 6038A purposes. | Checked |
Leave lines 1i blank unless filing a corporate consolidated return.
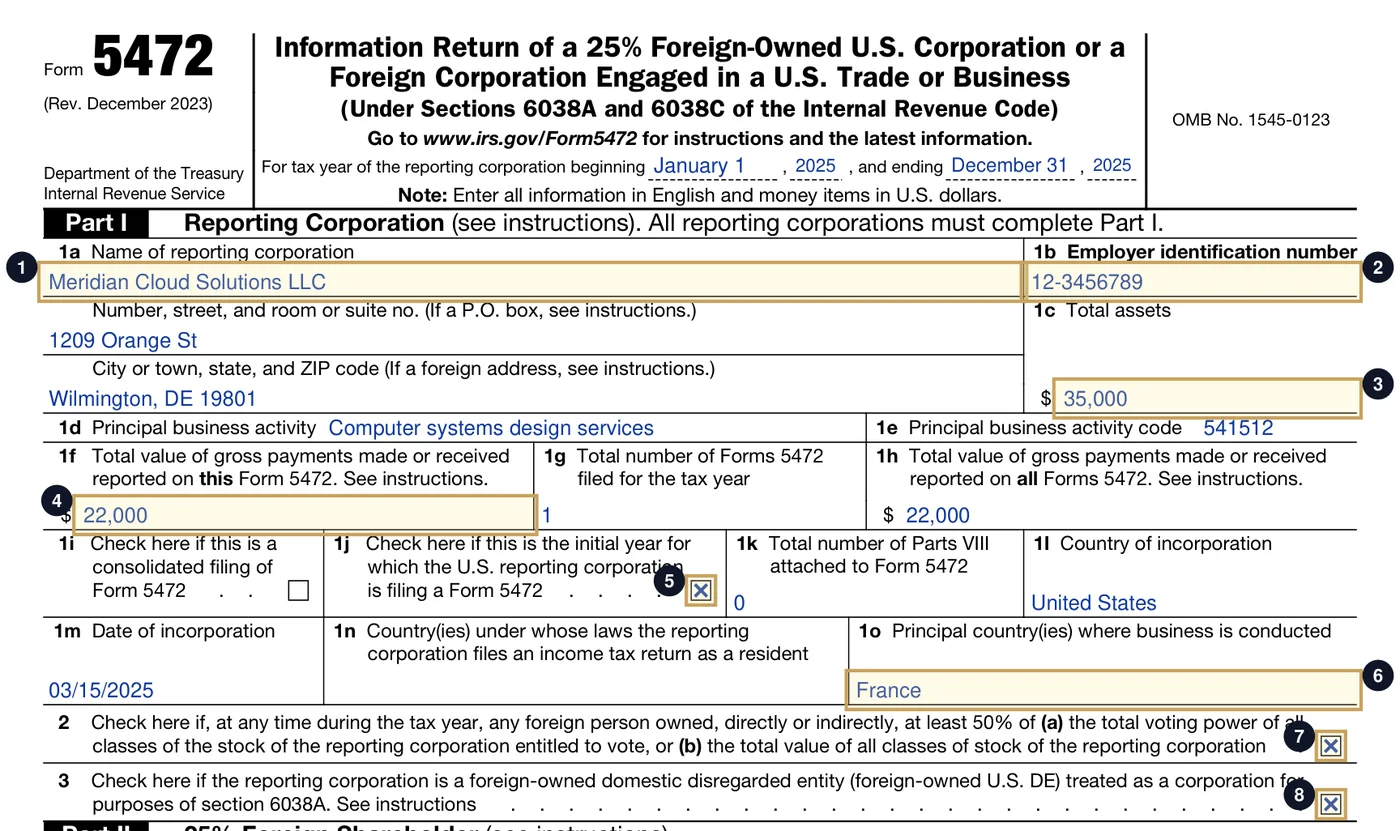
- 11a: the LLC's name and address
- 21b: the LLC's EIN
- 31c: total assets at year end ($35,000 in the example)
- 41f: $22,000, the Part V transactions (1h repeats it)
- 51j: checked, first Form 5472 the LLC files
- 61o: where the business is actually carried out
- 7Line 2: a foreign person owns at least 50%
- 8Line 3: foreign-owned U.S. DE
1n is left blank in the illustration: practice varies, confirm with your preparer.
Official IRS form, filled in with this guide's fictional example. Click to enlarge.Part II: 25% Foreign Shareholder
Report the foreign owner on lines 4a through 4e. Lines 5a to 5e are for a second direct 25% foreign owner, and lines 6a to 7e for the ultimate indirect owners (for example the people behind a foreign company that owns the LLC). If you own the LLC personally, leave lines 5a to 7e blank.
| Line | What the form asks | What to enter | Example |
|---|---|---|---|
| 4a | Name and address of direct 25% foreign shareholder | Your full personal legal name and non-US residential address. | Amélie Martin, 14 Rue de la Paix, Paris, France 75002 |
| 4b(1) | U.S. identifying number, if any | Your US ITIN or SSN, if you hold one. Otherwise leave blank. | Blank |
| 4b(2) | Reference ID number | For a foreign-owned LLC, the instructions say you "can" enter one; the FTIN on 4b(3) is the main identifier. Many preparers still create one, especially when there is no FTIN: letters and digits only, no spaces, 50 characters maximum, the same every year. No need to ask the IRS. | AMARTIN01 (optional) |
| 4b(3) | Foreign taxpayer identification number (FTIN), if any | A foreign-owned LLC must enter the owner's FTIN here, and use it consistently every year. If you have none, write "None" or "N/A". | 1234567890123 |
| 4c | Principal country(ies) where business is conducted | Country where you perform business activities. | France |
| 4d | Country of citizenship, organization, or incorporation | Your country of nationality. | France |
| 4e | Country(ies) where resident for tax purposes | Country where you file your personal local income tax return. | France |
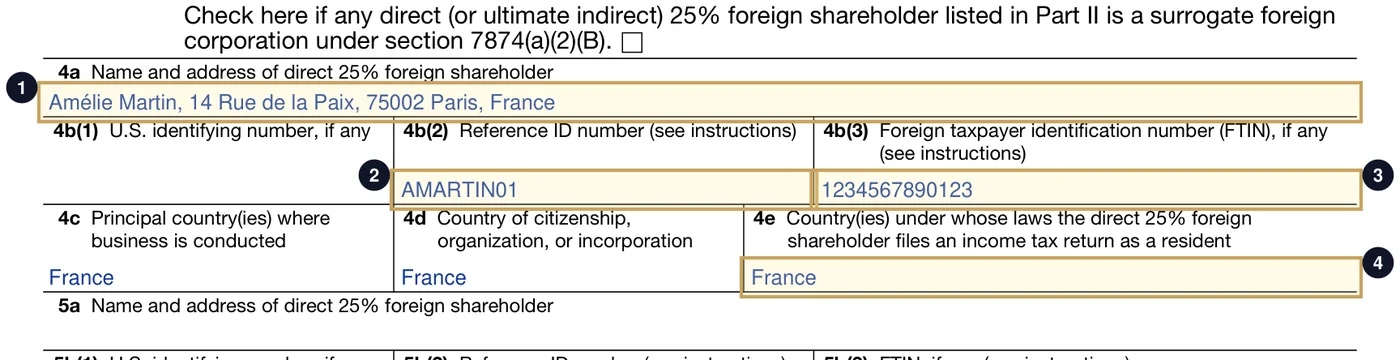
- 14a: your name and foreign address
- 24b(2): optional reference ID
- 34b(3): your FTIN (required for a foreign-owned LLC, or "None")
- 44e: your country of tax residence
Part III: Related Party
Part III identifies the person or company on the other side of the reportable transactions. For a single-member LLC transacting directly with its founder, the related party is the founder herself.
Check the box indicating whether the related party is a foreign person or a U.S. person. For a foreign founder, check foreign person.
| Line | What the form asks | What to enter | Example |
|---|---|---|---|
| 8a | Name and address of related party | Enter your personal legal name and residential address. | Amélie Martin, Paris, France |
| 8b(1) | U.S. identifying number, if any | Enter your ITIN or SSN if applicable. Otherwise leave blank. | Blank |
| 8b(2) | Reference ID number | If you created a reference ID for Part II, repeat it here. | AMARTIN01 (optional) |
| 8b(3) | FTIN, if any | Enter your foreign tax identification number. | 1234567890123 |
| 8c / 8d | Principal business activity and code | If the related party is an individual owner, enter your profession or N/A. |
Software consulting / 541512 |
| 8e | Relationship | Check the boxes that apply. The owner is the 25% foreign shareholder; many preparers also check Related to reporting corporation. | "25% foreign shareholder" (and often "Related to reporting corporation") |
| 8f | Principal country(ies) where business is conducted | Your primary country of business activity. | France |
| 8g | Country(ies) of tax residence | The country where you pay personal taxes. | France |
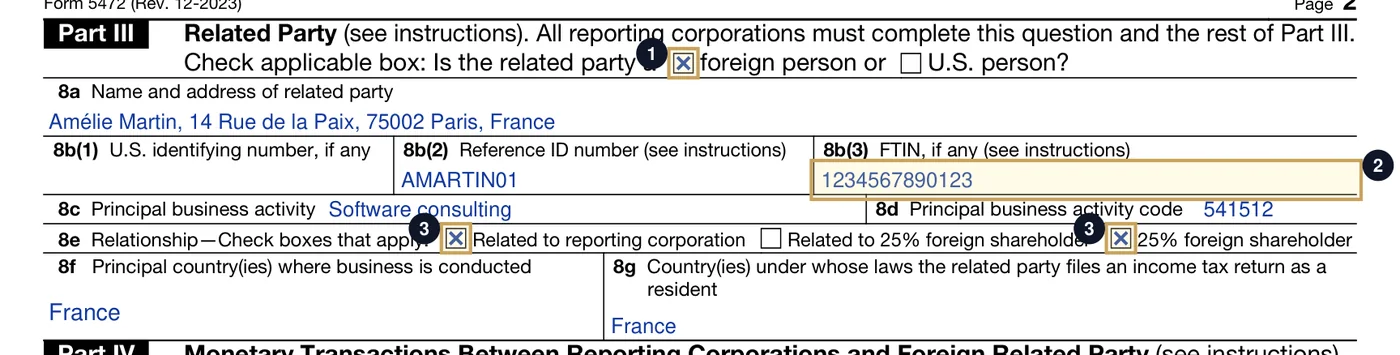
- 1"foreign person" checked
- 28b(3): the same FTIN as in Part II
- 38e: 25% foreign shareholder (and, often, related to reporting corporation)
Part IV: Monetary Transactions Between Reporting Corporations and Foreign Related Party
Part IV is for money that moves between the LLC and you as part of the business itself: for example the LLC paying you a fee for services (line 29), buying stock from your foreign company (line 23), or lending you money (line 31). Sales to and purchases from unrelated customers or suppliers never go here.
Be careful with lines 21 ("Other amounts received") and 35 ("Other amounts paid"). The instructions say to include amounts there only "to the extent that these amounts are taken into account in determining the taxable income of the reporting corporation." Money you put into the LLC as capital, and money you take out as distributions, does not fit that description. Those go in Part V instead (see below).
Because you checked "foreign person" in Part III, the form asks you to complete Part IV. Enter the lines that apply to you. If none apply, lines 22 and 36 total zero.
| Line | What the form asks | What to enter | Example |
|---|---|---|---|
| 15 | Consideration received for technical, managerial, engineering, construction, scientific, or like services | Fees the LLC received from you or your foreign company for services the LLC performed. | None |
| 29 | Consideration paid for technical, managerial, engineering, construction, scientific, or like services | Fees the LLC paid you or your foreign company for services (for example a monthly management fee). | None |
| 31 | Amounts loaned | Loans from the LLC to you, using the outstanding balance or monthly average method. | None |
| 17 | Amounts borrowed | Loans from you to the LLC, same methods. | None |
| 22 | Total. Combine amounts on lines 9 through 21 | Total received. | 0 |
| 36 | Total. Combine amounts on lines 23 through 35 | Total paid. | 0 |
Small amounts: if a type of transaction with the related party does not exceed $50,000 in total, the instructions allow you to report it as "$50,000 or less." Reasonable estimates (between 75% and 125% of the actual amount) are also allowed when exact figures cannot be determined; check the "estimates" box if you use them.
Part V: Reportable Transactions of a Foreign-Owned U.S. DE
This part exists only for foreign-owned disregarded LLCs, and for most founders it is the most important one. The instructions say you must check the box if the LLC "had any other transaction, as defined by Regulations section 1.482-1(i)(7) not already entered in Part IV. These transactions include amounts paid or received in connection with the formation, dissolution, acquisition, and disposition of the entity, including contributions to, and distributions from, the entity. Describe these on an attached statement."
In practice:
- Check the box in Part V.
- Attach a statement titled for example "Form 5472, Part V, Reportable transactions of a foreign-owned U.S. DE", with the LLC's name and EIN. List each type of transaction with its total in US dollars for the year: capital you contributed, distributions you received, formation costs or state fees you paid personally for the LLC, expenses of the LLC you paid from your personal card.
- These amounts count in line 1f (see Part I).
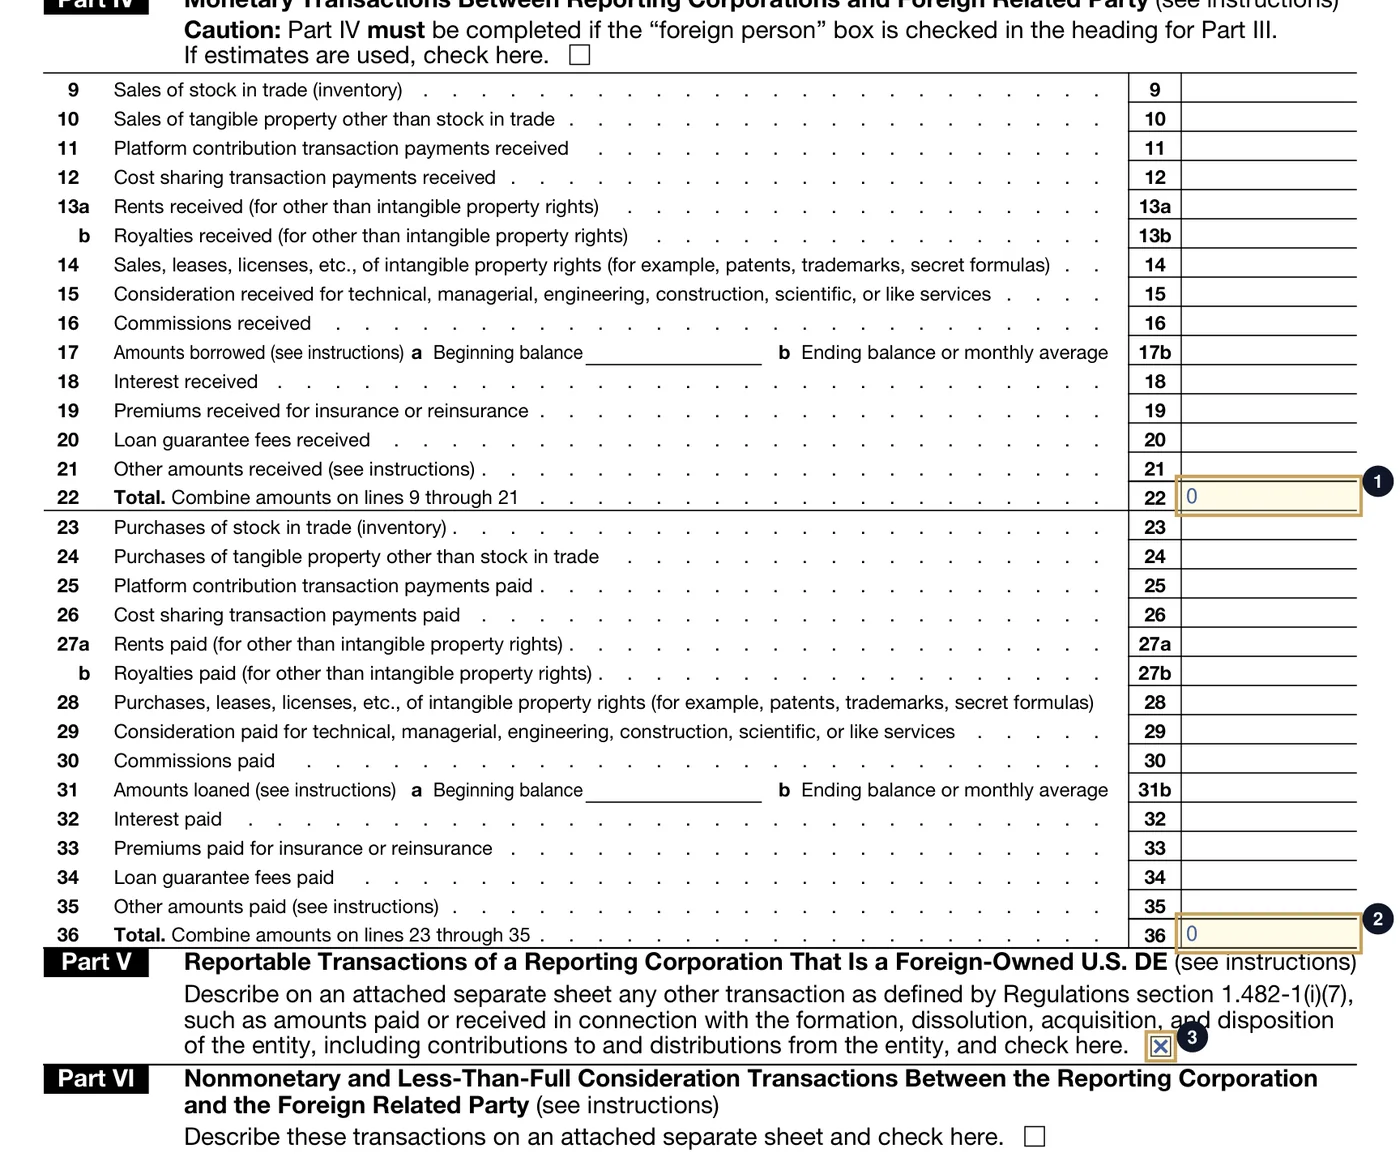
- 1Line 22: total received from the related party, 0 here
- 2Line 36: total paid to the related party, 0 here
- 3Part V: checked, with the statement attached
Here is what Amélie's Part V statement can look like:
Example attachment
Meridian Cloud Solutions LLC, EIN 12-3456789
Form 5472, Part V: reportable transactions of a foreign-owned U.S. DE
Tax year: January 1, 2025 to December 31, 2025
| Date | Transaction with Amélie Martin (sole owner) | Amount (USD) |
|---|---|---|
| 03/20/2025 | Capital contribution to the LLC (initial funding) | 5,000 |
| Various, 2025 | Distributions from the LLC to the owner | 17,000 |
| Total Part V transactions | 22,000 |
Amounts in US dollars. Exchange rates used for any foreign-currency transfer: attached schedule.
Part VI: Nonmonetary and Less-Than-Full Consideration Transactions
Complete this section only if you exchanged non-cash property, barter services, or digital assets with the LLC without full cash consideration. If none, leave the checkbox blank and proceed.
Part VII: Additional Information
All reporting corporations must answer the questions in Part VII:
- Line 37: Check No (unless you physically import commercial goods into the US from yourself or your foreign company).
- Line 38a–c: Leave blank if Line 37 is No.
- Line 39: Check No (cost sharing arrangements do not apply to standard freelance or SaaS LLCs).
- Line 40a: Check No (disallowed interest/royalty deductions under Section 267A).
- Line 41a: Check No (unless making an explicit Section 250 FDII claim).
- Line 42a & 42b: these questions are about loans between the LLC and you (or another related party) and the interest rate used. With no loan, check No to both. If you lent money to the LLC or borrowed from it, even without interest, read the instructions for lines 42a and 42b with your preparer before answering.
- Line 43a & 43b: Do not complete. The instructions specifically instruct: "Do not complete these lines if the reporting corporation is a foreign-owned U.S. DE."
Parts VIII and IX
- Part VIII (Cost Sharing Arrangement): Leave blank.
- Part IX (Base Erosion Payments, Section 59A): these lines concern the base erosion rules that target large corporations. For a typical founder LLC they are left blank; check the instructions if the LLC makes large deductible payments to foreign related parties.
Worked example
To see how these rules apply in practice, let us examine a typical founder scenario.
Amélie Martin is a French tax resident living in Paris. On March 15, 2025, she formed Meridian Cloud Solutions LLC, a Delaware single-member LLC providing cloud software architecture consulting.
During 2025, her cash flows were as follows:
- Formation & Setup: Amélie deposited $5,000 from her personal French account into the LLC's US business bank account as startup capital.
- Commercial Revenues: The LLC received $50,000 from corporate clients in the UK and Germany. Because these transactions were with unrelated third parties, they are not reported on Form 5472.
- Operating Expenses: The LLC paid $3,000 to third-party software vendors (AWS, Stripe). These third-party costs are not reported on Form 5472.
- Owner Distributions: Amélie transferred $17,000 from the LLC bank account to her personal account in France as profit distributions.
How the numbers flow to the forms:
Pro Forma Form 1120:
- Amélie writes "Foreign-owned U.S. DE" at the top.
- She enters "Meridian Cloud Solutions LLC", the Delaware address, and EIN
12-3456789. - Box E(1) is checked for an initial return.
- Income and deduction lines 1 through 37 remain completely blank.
- She signs the bottom as "Sole Member".
Form 5472:
- Part I, Line 1c (Total assets): $35,000 (the cash left in the LLC bank account on December 31: $5,000 + $50,000 − $3,000 − $17,000).
- Part I, Line 1f & 1h (Total gross payments): $22,000 (the Part V transactions: $5,000 capital contribution + $17,000 distribution).
- Part I, Line 1j: Checked (first year the LLC files Form 5472).
- Part I, Lines 2 and 3: Checked (foreign owner of at least 50%, and foreign-owned U.S. DE).
- Part II & III: Amélie lists herself, her French address and her French FTIN (she has no ITIN). She also chooses to add the reference ID
AMARTIN01and will reuse it every year. - Part IV: no business transactions with Amélie (she did not invoice the LLC, borrow from it or sell it anything), so lines 22 and 36 total zero.
- Part V: Checked, with an attached statement detailing the $5,000 contribution and $17,000 distribution.
- Part VII: Lines 37, 39, 40a, 41a, and 42 checked "No". Lines 43a–43b left completely blank.
How and where to file
Foreign-owned US disregarded entities cannot file Form 5472 electronically through regular tax software. You must submit your packet by fax or mail using the dedicated IRS intake unit.
Dedicated Filing Methods
Assemble your packet in this order:
- Pro forma Form 1120 (with "Foreign-owned U.S. DE" written at the top and signed).
- Form 5472.
- Attached statements (such as the Part V explanation).
Submit via one of the two official channels:
- By fax: Fax your complete document package to: 855-887-7737 (transmission resolution must be 300 DPI or higher).
- By Mail:
Send via postal service or courier to:
Internal Revenue Service1973 Rulon White BlvdM/S 6112 Attn: PIN UnitOgden, UT 84201
Do not use the general corporate filing addresses listed in the Form 1120 instructions.
Deadlines and Extensions
- Standard Deadline: Form 5472 follows the federal corporate income tax deadline, which is generally April 15 following the close of the calendar tax year.
- Requesting an Extension: You can obtain an automatic 6-month extension by filing Form 7004 (PDF).
- On Form 7004, Part I, Line 1, enter Form Code 12 (the code for Form 1120).
- Write "Foreign-owned U.S. DE" across the top of Form 7004.
- Enter
-0-on lines 6, 7, and 8. - You must fax or mail Form 7004 to the same Ogden, UT fax number or address shown above by the regular due date.
- An extension moves your filing deadline to October 15.
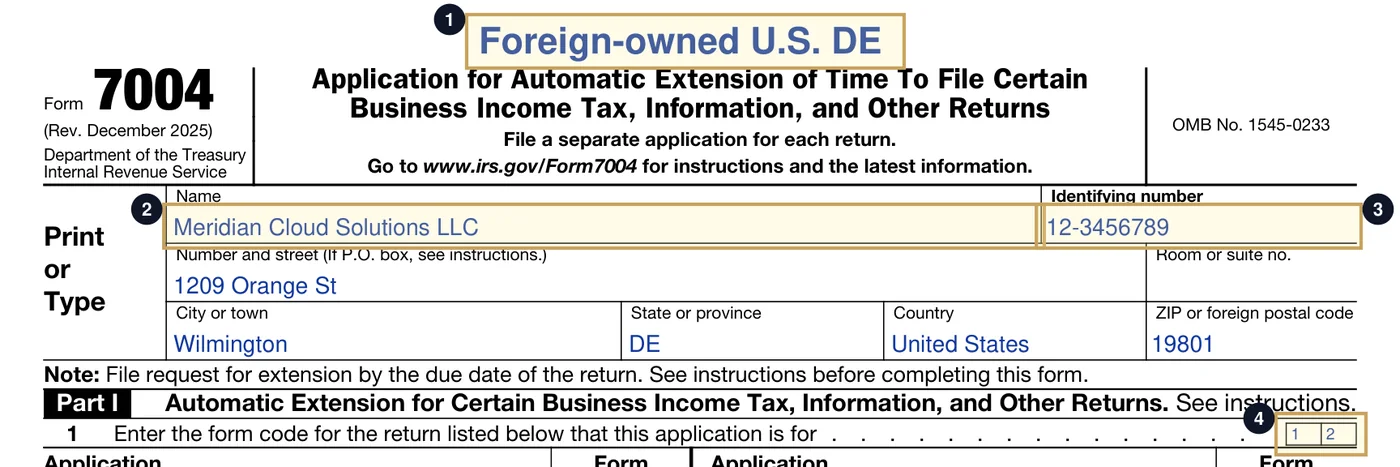
- 1"Foreign-owned U.S. DE" written across the top
- 2Name of the LLC
- 3Identifying number: the LLC's EIN
- 4Line 1: form code 12 (Form 1120)
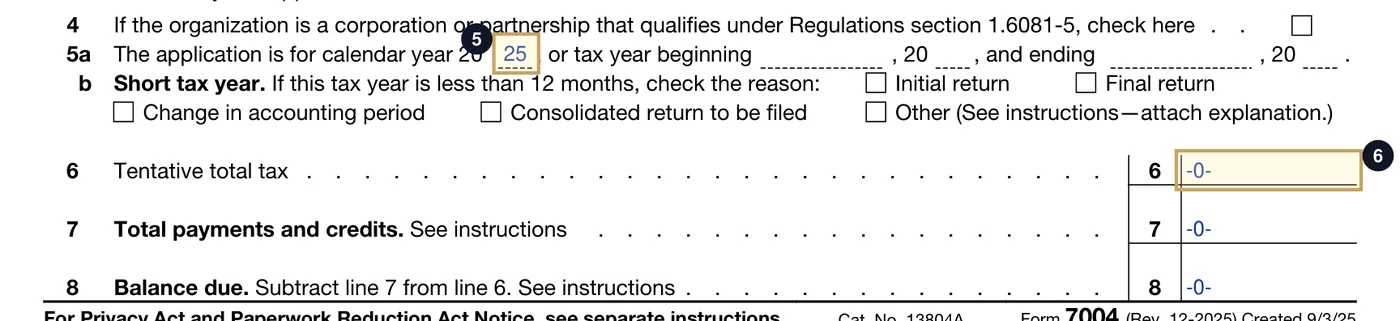
- 1Line 5a: calendar year 2025
- 2Line 6: tentative total tax, -0-
Lines 7 and 8 also show -0-.
Official IRS form, filled in with this guide's fictional example. Click to enlarge.Records you must keep
The instructions say a reporting corporation "must keep the permanent books of account or records as required by section 6001", sufficient to establish the correct treatment of transactions with related parties. The IRS manual adds that these records generally must be kept in the United States; records kept abroad are acceptable if they are produced (or brought to the US) within 60 days of an IRS request. A missing-records failure carries the same $25,000 penalty as a missing form.
Proof of Filing
Keep your own proof of filing, permanently:
- A complete PDF copy of the exact package sent.
- The transmission confirmation sheet generated by your fax service showing date, time, and successful delivery.
- If mailed, registered mail or courier delivery tracking receipts confirming arrival at the Ogden PIN Unit.
Common mistakes to avoid
- Filing Form 5472 alone: for a foreign-owned LLC, Form 5472 must be attached to a pro forma Form 1120. A penalty applies when the form is not filed "in the manner prescribed".
- Filling in the income lines of Form 1120: the instructions only ask for the name, address and items B and E. Entering revenue or deductions turns a pro forma return into something that looks like a real corporate return and invites confusing IRS letters.
- Reporting third-party customer sales in Part IV: lines 9 through 36 are only for transactions between the LLC and the foreign related party (you). Customer revenue does not belong here.
- Putting contributions and distributions on lines 21 and 35: those lines are limited to amounts that affect the LLC's taxable income. Capital in and out goes in Part V, with an attached statement.
- Skipping years with no revenue: if money moved between you and the LLC (capital you put in, money you took out, LLC fees you paid personally), Form 5472 is required even if the LLC had no sales.
- Mailing to the standard Form 1120 address: the instructions say foreign-owned U.S. DEs "do not use the mailing address provided in the Instructions for Form 1120". Use the fax number or the Ogden PIN Unit address.
- Forgetting to check Part I, Line 3: this box tells the IRS the return comes from a foreign-owned disregarded LLC. Leaving it blank makes the filing harder to process correctly.
- Leaving the FTIN box empty: a foreign-owned LLC must enter the owner's FTIN on 4b(3), or "None"/"N/A" if there is none. Use the same identifiers every year.
Your checklist
- Obtain your LLC's legal documents and verify the official EIN issued by the IRS.
- Calculate all cash movements between your personal accounts and the LLC bank account during the tax year.
- Download the current official versions of Form 1120 and Form 5472.
- Prepare the pro forma Form 1120: enter name, address, EIN, check Box E, and write "Foreign-owned U.S. DE" across the top.
- Sign and date page 1 of Form 1120. Leave all financial schedules blank.
- Complete Form 5472: fill Parts I, II, III, IV, V, and VII.
- Prepare a brief statement for Part V detailing owner contributions and distributions.
- If extra time is required, file Form 7004 before the April deadline to extend to October.
- Fax the combined packet to the IRS PIN Unit at 855-887-7737.
- Archive the complete signed packet along with the successful fax transmission confirmation sheet.
Official resources
- Form 5472 (PDF): The official information return for foreign-owned entities.
- Instructions for Form 5472 (PDF): Detailed line-by-line rules, definitions, and filing requirements.
- About Form 5472: IRS landing page with updates and revisions.
- Form 1120 (PDF): The corporate income tax return used as the required pro forma cover return.
- Form 7004 (PDF): The application for an automatic 6-month filing extension.
- Instructions for Form 7004 (PDF): Rules and procedures for requesting a business filing extension.
- Form SS-4 (PDF): Application for an Employer Identification Number.
- Apply for an EIN: Official IRS overview of the EIN application process.
Frequently asked questions
What is the penalty for filing Form 5472 late?
A $25,000 penalty is assessed for failing to file Form 5472 when due and in the manner prescribed. Filing a substantially incomplete Form 5472 counts as a failure to file. If the IRS issues a failure notice and the return is not submitted within 90 days, an additional $25,000 penalty applies, for each related party, for every 30-day period (or part of one) the failure continues.
Can I file Form 5472 electronically?
No. Foreign-owned U.S. disregarded entities cannot use standard electronic filing methods. You must submit your pro forma Form 1120 and Form 5472 by fax or mail directly to the IRS Ogden PIN Unit.
Do I have to file if my LLC had no transactions at all?
If the LLC had zero financial activity, no bank accounts opened, no capital contributions, no startup expenses paid by the owner, and no fees paid, there are technically no reportable transactions under Regulations Section 1.482-1(i)(7). The instructions confirm that a foreign-owned LLC with no reportable transactions of the types in Parts IV, V and VI does not have to file. In practice, most founders do have at least one: the money used to form or fund the LLC, or LLC fees paid from a personal account. Check each year carefully before deciding not to file.
Does filing Form 5472 mean my LLC has to pay US income tax?
No. Form 5472 and the pro forma Form 1120 are strictly informational filings under Section 6038A. A disregarded entity owned by a nonresident is not subject to US corporate income tax simply because it files these forms. Whether you owe personal US income tax depends on whether your activities generate income effectively connected with a US trade or business (see our guide on the 1040-NR).
Filing US tax paperwork from abroad can feel daunting, but once you break down each form into concrete steps, the process is straightforward. If you want professional assistance preparing your annual reporting, explore our Form 5472 + Pro Forma 1120 service or request a free preliminary check to confirm your filing obligations.
Keep reading
Missed Form 5472 for Past Years? Step-by-Step Catch-Up Guide
Missed Form 5472 filings? Discover how to catch up on late Form 5472 filing, prepare pro forma Form 1120, submit reasonable cause, and handle IRS penalties.
Read the guide1040-NR Foreign LLC Owner: Do You Need to File?
Wondering if you must file Form 1040-NR as a foreign LLC owner? Learn how ECI, US trade or business status, and tax treaties affect your return.
Read the guideThis article is general information about US tax rules for foreign-owned LLCs, not advice for your specific situation. Rules change; check the date above and ask before you file.